Auto insurance
Liability, comprehensive and collision on one policy, with uninsured motorist written to match your bodily injury limits.
- BI / PD limits
- 100/300/50
- Comp / coll deduct.
- $500 / $500
- UM / UIM
- 100/300
$1,284 / yrSample. Not a quote.
Product family
Liability, comprehensive and collision on one policy, with uninsured motorist written to match your bodily injury limits.
$1,284 / yrSample. Not a quote.
HO-3 and HO-5 forms with replacement cost on the dwelling, and a separate wind and hail deductible written in plain figures.
$1,616 / yrSample. Not a quote.
HO-4 contents and liability coverage that follows you off the property, plus loss of use if the building becomes uninhabitable.
$214 / yrSample. Not a quote.
HO-6 walls-in coverage sized against your association master policy, including loss assessment for shared structure claims.
$486 / yrSample. Not a quote.
Personal liability that attaches above your auto and home limits and pays after those limits are exhausted.
$317 / yrSample. Not a quote.
Level term for the years the mortgage and the kids overlap, or whole life when the need does not have an end date.
$38 / moSample. Not a quote.
Separate physical damage and liability for the things a homeowners policy explicitly will not cover.
$472 / yrSample. Not a quote.
A BOP packaging general liability, business personal property and business income for small operations under 100 employees.
$1,940 / yrSample. Not a quote.
Policy familyIM‑1948
Auto, home, renters, condo, umbrella, life and business, written as one programme out of Cleveland since 1948 — and checked at the joints, where cover bought one policy at a time comes apart.
Declarations — specimen
Ironclad Mutual
Cleveland, OH · admitted carrier
Cover bought one policy at a time comes apart at the joints: an umbrella that will not attach because the underlying limit is too low, a watercraft value a homeowners form was never going to carry, two deductibles for one storm. We write the whole assembly and check where the pieces meet.
A liability award does not land on one policy. It climbs a stack. Auto answers first, up to its per-person limit; the umbrella attaches above that limit, and only if the underlying limit is at least the figure the umbrella requires. Lower the auto limit to save forty dollars a year and you can open a gap the umbrella will not bridge.
Personal liability, one injured claimant
Move the slider to see which limit pays.
Illustrative arithmetic on the limits shown, not a quote and not legal advice. Real limits, forms, required underlying limits and exclusions vary by state filing and by policy. A self-insured retention of $250 applies to a claim the underlying policies do not cover at all.
Turn any card over. The exclusions on the back are the standard ones the ISO-family forms these products are modelled on actually carry — not a shortened, friendlier version of them. If a gap on a back matters to your household, there is usually an endorsement that closes it, and it is named.
Liability, comprehensive and collision on one policy, with uninsured motorist written to match your bodily injury limits.
Usual buy-backRideshare endorsement, for the period between accepting a fare and dropping it.
HO-3 and HO-5 forms with replacement cost on the dwelling, and a separate wind and hail deductible written in plain figures.
Usual buy-backWater backup endorsement, service line coverage, and ordinance or law at 25 per cent.
HO-4 contents and liability coverage that follows you off the property, plus loss of use if the building becomes uninhabitable.
Usual buy-backScheduled personal property for a ring, an instrument or a bicycle.
HO-6 walls-in coverage sized against your association master policy, including loss assessment for shared structure claims.
Usual buy-backHigher loss assessment, and units-owners building property to match the master deed.
Personal liability that attaches above your auto and home limits and pays after those limits are exhausted.
Usual buy-backRaise the underlying auto and homeowners limits so the umbrella can attach.
Level term for the years the mortgage and the kids overlap, or whole life when the need does not have an end date.
Usual buy-backConvert to permanent cover before the conversion window closes.
Separate physical damage and liability for the things a homeowners policy explicitly will not cover.
Usual buy-backAgreed value on the hull, and an extended navigation endorsement.
A BOP packaging general liability, business personal property and business income for small operations under 100 employees.
Usual buy-backCyber and data breach, EPLI, and hired and non-owned auto.
Every figure below is a real term on a real form: limits, deductibles, valuation basis and the point at which an umbrella attaches. Move the selector to compare the rungs, or open one to read the whole sheet.
Priced against one household: two adults, two vehicles, a 1,940 sq ft single family home built 1958 in Cuyahoga County, Ohio, no claims in five years, no youthful operators.
Auto plus renters or home at limits that clear a routine loss. The floor we are willing to write.
Liability
Auto physical damage
The bundle most households actually need. Umbrella attaches, deductibles halve, one deductible per event.
Liability
Auto physical damage
Written for households with real assets to protect. Extended replacement cost, $2M umbrella, annual review.
Liability
Auto physical damage
Drag the selector, use the arrow keys, or open a tier. Every figure is illustrative and is not a quote.
She read my association master policy and my BOP side by side before quoting. Nobody had done that in nineteen years.
Drag the handle, or use the arrow keys.
Every carrier in the United States tells you it is trustworthy. Two independent sources will tell you whether that is true, and neither of them is the carrier. Look both up before you buy anything from anyone, us included.
The NAIC publishes a complaint index for every licensed carrier, normalised so that 1.00 is the median for a company of that size. AM Best publishes a financial strength rating that estimates the carrier's ability to pay claims when a bad year arrives all at once.
Cleveland office, personal lines desk
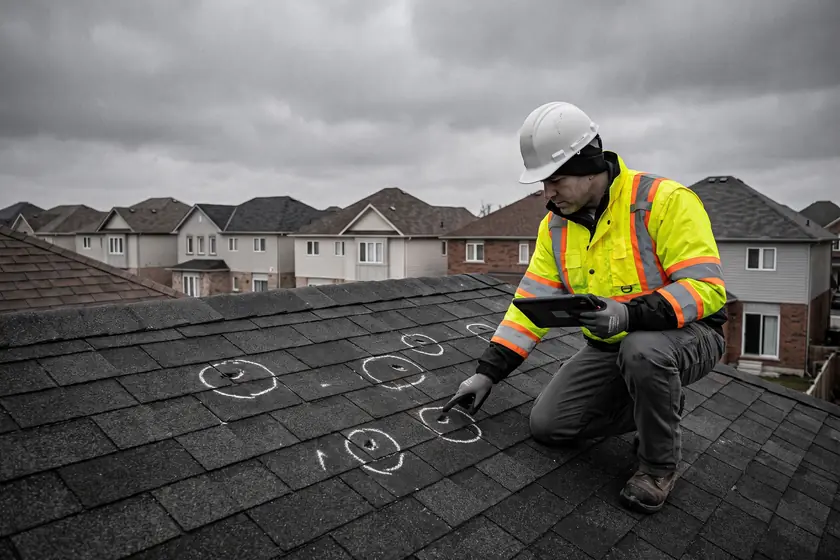
Hail inspection, Cuyahoga County
When a storm takes the roof and both vehicles in the same afternoon, two carriers means two deductibles, two adjusters and two versions of what happened. On an IM-2 or IM-3 programme it is one event: we apply the higher deductible and waive the other, and one adjuster owns the whole file.
Three separate limits on an auto policy, written in thousands. 100 is the most we pay for bodily injury to any one person in an at-fault accident. 300 is the most we pay for bodily injury across everyone hurt in that one accident. 50 is the most we pay for damage to other people’s property. Ohio requires 25/50/25. A single overnight stay in a trauma unit can exceed that, and the balance is yours.
An HO-3 covers the structure against open perils and your belongings against a named list. An HO-5 covers both on an open perils basis. In practice that means an HO-3 asks you to prove your loss was caused by something on the list, while an HO-5 asks us to prove it was caused by something excluded. An HO-4 is the renters version, an HO-6 is the condo version.
It matters most on old things. Actual cash value pays what the item was worth the moment before the loss, with depreciation subtracted. Replacement cost pays what an equivalent new item costs today. On a twenty-two year old roof, actual cash value can settle at less than a third of the replacement figure, and the difference comes out of your pocket.
Only after the underlying policy is exhausted. If you carry 250/500/100 auto liability and a judgment lands at $700,000 for one injured person, the auto policy pays its $250,000 and the umbrella picks up the next $450,000. That attachment structure is why an umbrella is inexpensive, and why we require specific underlying limits before we will write one.
When one storm damages your house and your car, two policies would normally each take a deductible. On our IM-2 and IM-3 bundles, one event means one deductible: we apply the higher of the two and waive the other. It is the practical reason most of our policyholders end up with everything on one carrier.
Two public sources, neither of them us. The NAIC Consumer Information Source publishes a complaint index for every carrier, where 1.00 is the industry median and lower is better. AM Best publishes a financial strength rating that estimates the carrier’s ability to pay claims. Look both up for any carrier you are considering, including this one, before you sign anything.
Four steps, about sixty seconds, and no obligation. An agent reads every line together so the limits actually meet.
Nothing here binds cover. No data leaves your browser on this demonstration site.
Storage on this device
No cookies, no analytics, no third-party scripts, nothing shared with anybody. This site would like to keep four choices in your browser: theme, ink, lettering and your reading options. Decline and everything still works — it just forgets when you leave.Privacy notice
Form LW-1 · amendment to this page
Recolour this site in front of you. Every ink below was checked against both themes before it was offered, so nothing is corrected after you pick it.
Pure grounds, and every muted ink pulled up to the primary.
Stills the peril field, the parallax and every scroll-driven animation. Starts from your system setting.
Every link in the body and the footer, always underlined.
These are preferences, not a conformance claim. This site has not been audited against WCAG and says nowhere that it has been.